Condo Fees Explained: What First-Time Buyers Actually Pay For
The monthly fee is the line first-time buyers flinch at — what it actually buys (the building's insurance, the reserve fund, the elevators you're standing in), how it's calculated, and the two numbers that tell you whether a building is healthy.
What a condo fee actually is
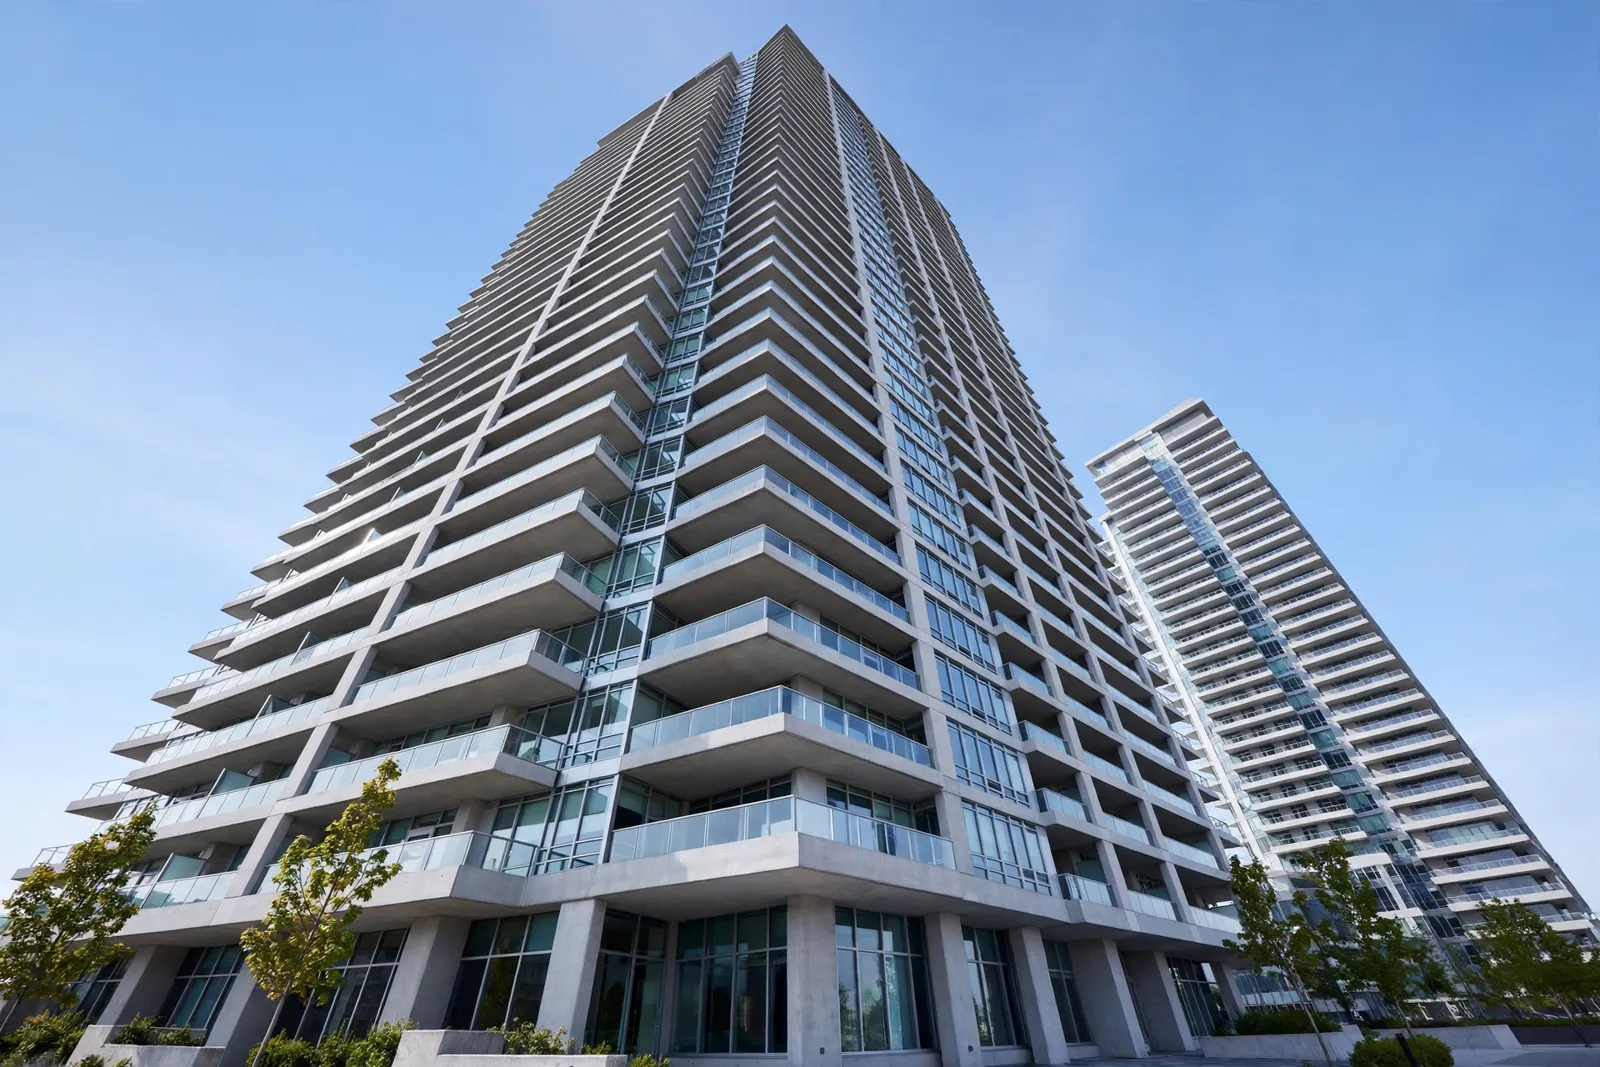
When you buy a condo, you own your unit — and a share of everything else. The corporation owns and runs the common elements: the lobby, elevators, garage, roof, hallways, gym and grounds. All of that runs on a budget, set each year by the corporation's board, and your monthly fee is your share of it. The split isn't negotiated and it isn't about how much you use the gym. It's fixed by the unit factor in the condo's declaration — roughly, your unit's proportion of the whole building, which tracks its size and value. A bigger unit carries a bigger percentage and pays more: a penthouse and a studio in the same building can have fees several times apart, while riding the same elevators.
Where the money goes
- The building's insurance. One policy covering the structure and common elements — often one of the budget's largest lines, and one that has been climbing.
- Common-area utilities. Heat, water and power for hallways, garage, amenities and the building's systems; in some buildings, your unit's heat or water too.
- Cleaning, security and concierge. The people who keep the building running day to day.
- Amenities. The pool, gym, sauna, party room and guest suites cost money to run, heat, clean and eventually replace — whether you use them or not.
- Management and administration. The management company, accounting, legal and the audit.
- The reserve fund. The line that matters most over time — covered next.
The reserve fund is the part that matters most
Think of the reserve fund as the building's long-term savings account, and it is not optional: every Ontario condo corporation must maintain one, and must fund it according to a reserve fund study. That study is an engineer's plan that inventories the big components — roof, windows, garage structure, elevators, boilers and chillers — estimates when each will need repair or replacement and what it will cost, and sets out a funding plan to match. The study is updated on a regular cycle, because buildings age on schedule whether the budget admits it or not. A portion of every monthly fee flows into this account, untouched by day-to-day spending. When you read a building's finances, the reserve fund is where the truth lives.
Why fees rise
Budgets reset annually, and buildings get older in one direction. Early in a building's life the systems are new and the reserve contributions buy future work cheaply. As the building ages, the expensive items arrive together — windows at end of life, a garage membrane, elevator modernization — while insurance and utilities climb on their own schedules. Steady, moderate increases are normal and healthy. What should worry you is the opposite pattern: a fee that has barely moved in an aging building. That usually isn't efficiency. It's a board deferring contributions, and deferred maintenance doesn't disappear — it comes back as a sudden steep increase or a special assessment.
The two health checks before you buy
First, the reserve fund's trajectory in the status certificate. Before you buy, your lawyer reviews the status certificate — and its financial heart is the reserve fund: the current balance, the contributions planned over the coming years, and whether the certificate discloses expected increases or special assessments. A fund on plan, with contributions rising steadily toward known projects, is a healthy building. A thin fund with major work on the horizon means you'll pay for that work one way or another. Our walkthrough of the status certificate shows exactly what to look for.
Second, special assessments. When a major cost lands and the reserve can't cover it, the board can levy a one-time special assessment on every unit by unit factor, or add a temporary surcharge to the fees. Ask directly whether one is in place, planned, or even discussed — the answer is in the status certificate and the minutes it references.
Compare it honestly with a house
The fee feels like a pure extra because a house doesn't have one. But a house has no one to split the roof with, either. Insurance, snow clearing, the water heater, the driveway, the eventual windows — every line the condo fee bundles shows up in a house budget as a separate bill, usually arriving in lumps instead of monthly instalments. The fair comparison isn't fee versus zero. It's the fee versus the true monthly average of owning the whole building yourself, including the savings habit most house owners don't keep.
What the fee never covers
- Your own unit insurance. The building's policy covers the structure and common elements — not your belongings, your liability, or the upgrades inside your unit. You need your own policy on top of the fee: see home insurance in Ontario.
- In-unit repairs. Your appliances, your fixtures, your flooring — wear inside your four walls is yours.
- Your individual utilities, where your unit is separately metered, and your property taxes, which are always billed to you directly.
Red flags when you're shopping
- A special assessment already levied or disclosed as coming.
- A reserve fund running behind its study's plan, with big-ticket items due.
- Fees flat for years in an older building with no major work done — the bill is being postponed, not avoided.
- Litigation or insurance problems disclosed in the status certificate.
- Deferred maintenance you can see — tired hallways, a garage in rough shape. Buildings show their budgets.
The bottom line
A condo fee isn't a tax on convenience — it's the operating budget of a building you partly own, and unlike most budgets, you can read this one before you buy. Check the reserve fund, ask about assessments, and then price the fee into the same monthly math as your mortgage and taxes. That math is also where first-time buyers find real help: every first-home program, stacked, shows what your budget can include before you commit to a number.